Accounting in D365, Part 4: Acquire to Dispose
The complete fixed asset cycle in Dynamics 365 Finance & Operations: acquisition, depreciation, split and disposal, with the accounting entries at each stage.
This is Part 4 of the Accounting in D365 series. Parts 1 to 3 followed inventory from purchase through production to sale; this part follows a fixed asset through its full life. All transactions are in legal entity INMF (currency INR) in financial year 2026-27, and the trial balance opens with the closing balances of Part 3 (Order to Cash).
A fixed asset does not simply appear on the balance sheet and stay there. It is capitalised, depreciated, sometimes restructured and finally disposed of, and each of these events reaches the ledger in a different way. This post focuses on the accounting only: the entries posted at each stage, the effect on the fixed asset subledger and the general ledger, and the final impact on the Trial Balance, Profit and Loss statement and Balance Sheet. For the step-by-step process in D365, refer to the Acquire to dispose end to end cycle post.
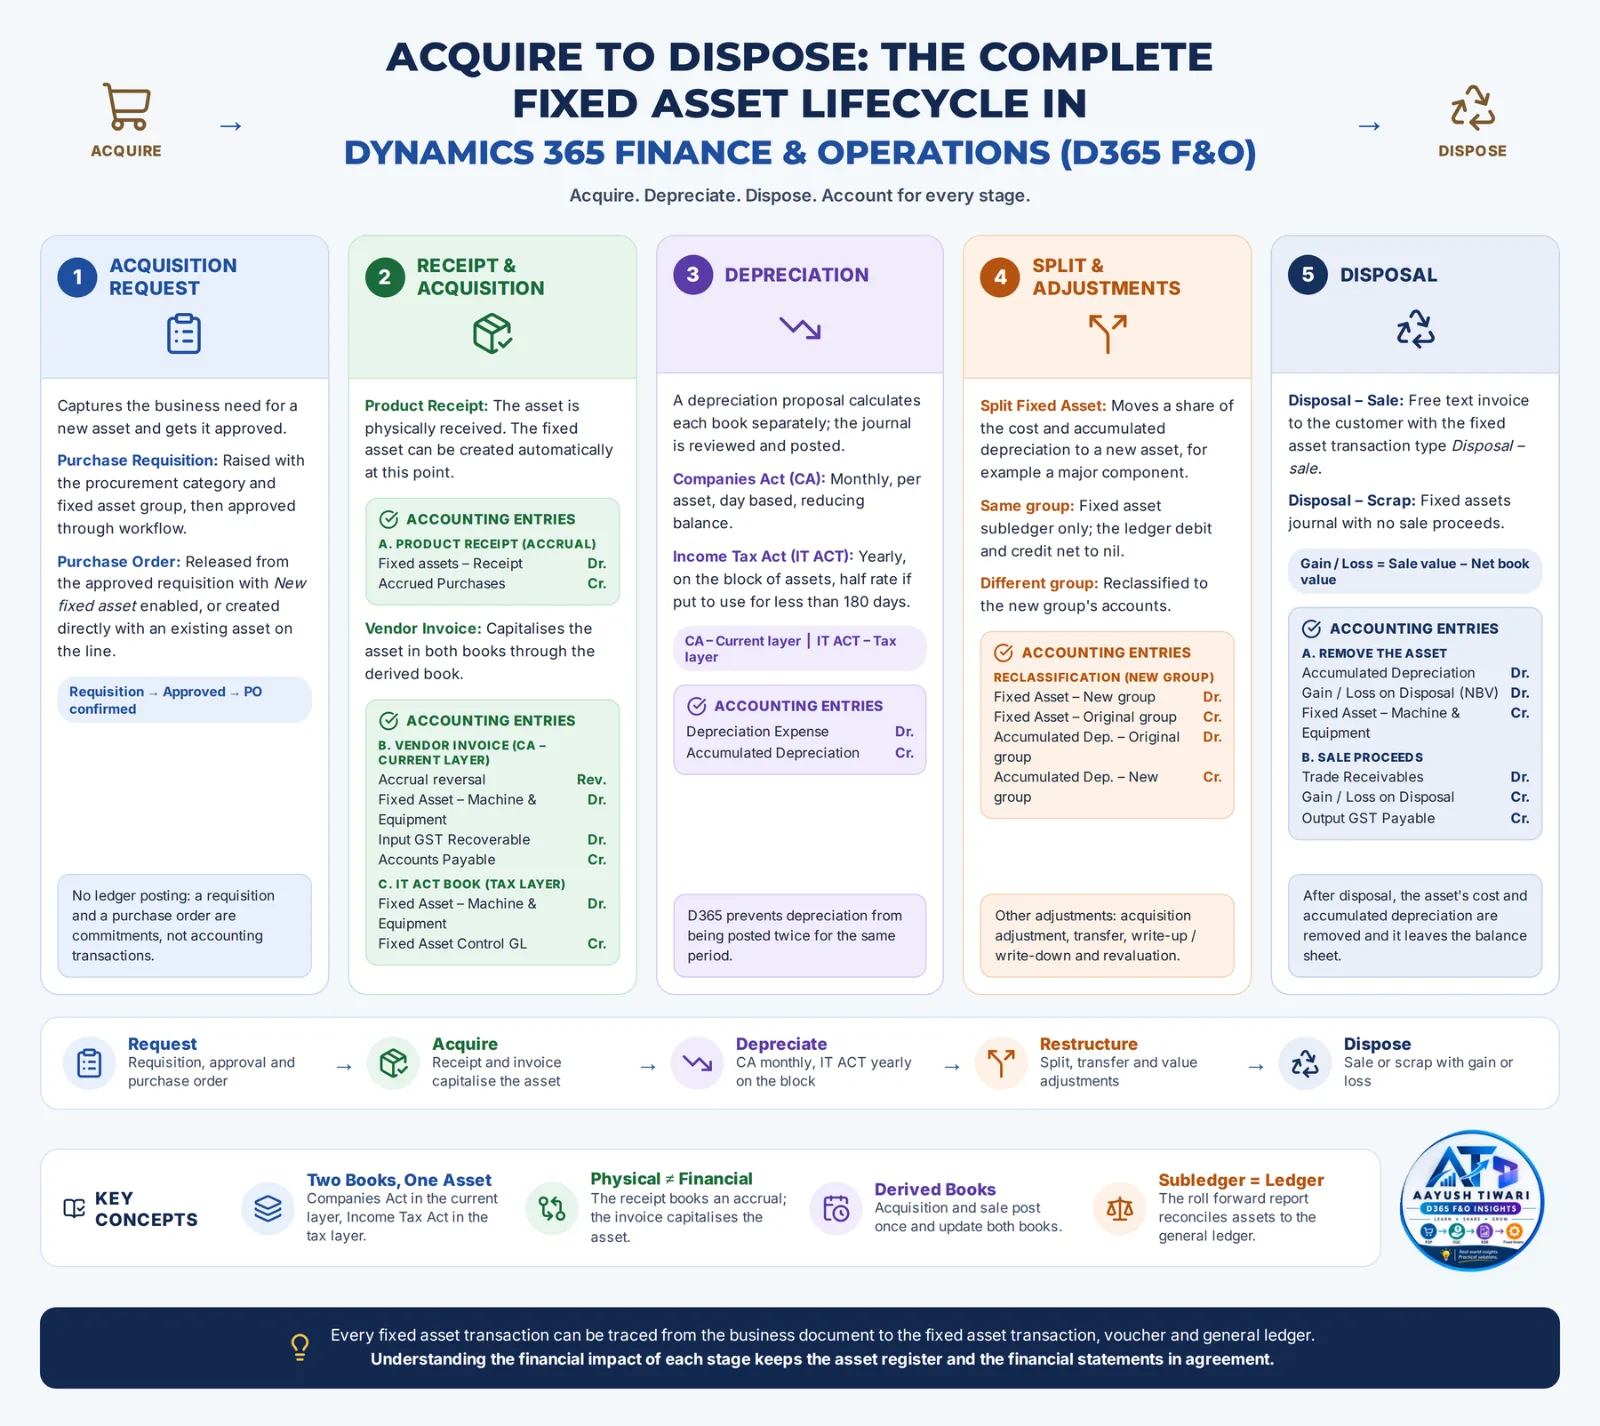
Acquire to Dispose cycle in D365 F&O
The scenario
Fixed asset | Name | Group | Event | Value (INR) |
|---|---|---|---|---|
ME-0004 | Equipment - 2 | M&E | Acquired through purchase requisition, 07-10-2026 | 5,00,000.00 |
ME-0003 | Equipment - 1 | M&E | Acquired through purchase order, 07-10-2026 | 2,00,000.00 |
ME-0005 | Equipment - 3 | M&E | Split from ME-0004 (50%), 31-03-2027 | 2,50,000.00 |
MEP-0001 | Part of Equipment - 2 | M&E_P | Split from ME-0004 (10%) to a new group, 31-03-2027 | 50,000.00 |
ME-0003 | Equipment - 1 | M&E | Sold to Wingtip Toys India Ltd., 31-03-2027 | 1,75,000.00 |
Both machines are purchased from Northwind Traders India Ltd. (INMF-000005). The purchase requisition and purchase orders are commitments and post no accounting, so the accounting starts at the product receipt.
Setup behind the entries
The accounting entries in this post are driven by configuration: fixed asset groups, books, depreciation profiles and the fixed asset posting profile. For the setup screens, refer to the Fixed assets Configurations post.
Indian companies maintain two depreciation records for every asset. D365 handles this with two books in separate posting layers:
Companies Act book (CA) | Income Tax Act book (IT ACT) | |
|---|---|---|
Posting layer | Current (feeds the financial statements) | Tax (statutory tax record) |
Depreciation profile | WDV@20: reducing balance at 20% | WDV@15: reducing balance at 15% |
Depreciation basis | Each asset, day based | Block of assets (asset group depreciation) |
Derived book | IT ACT, for Acquisition, Acquisition adjustment and Disposal - sale | – |
The posting profile maps each fixed asset transaction to the ledger:
Transaction | Debit | Credit |
|---|---|---|
Acquisition (CA) | Machine & Equipment | Vendor invoice (through the product receipt accrual) |
Acquisition (IT ACT) | Machine & Equipment | Fix assets control GL |
Depreciation | Depreciation Expense - Tangible Assets | Accumulated Depreciation - Machine & Equipment |
Disposal - sale, net book value | Gain & Loss - Disposal of Assets | Machine & Equipment |
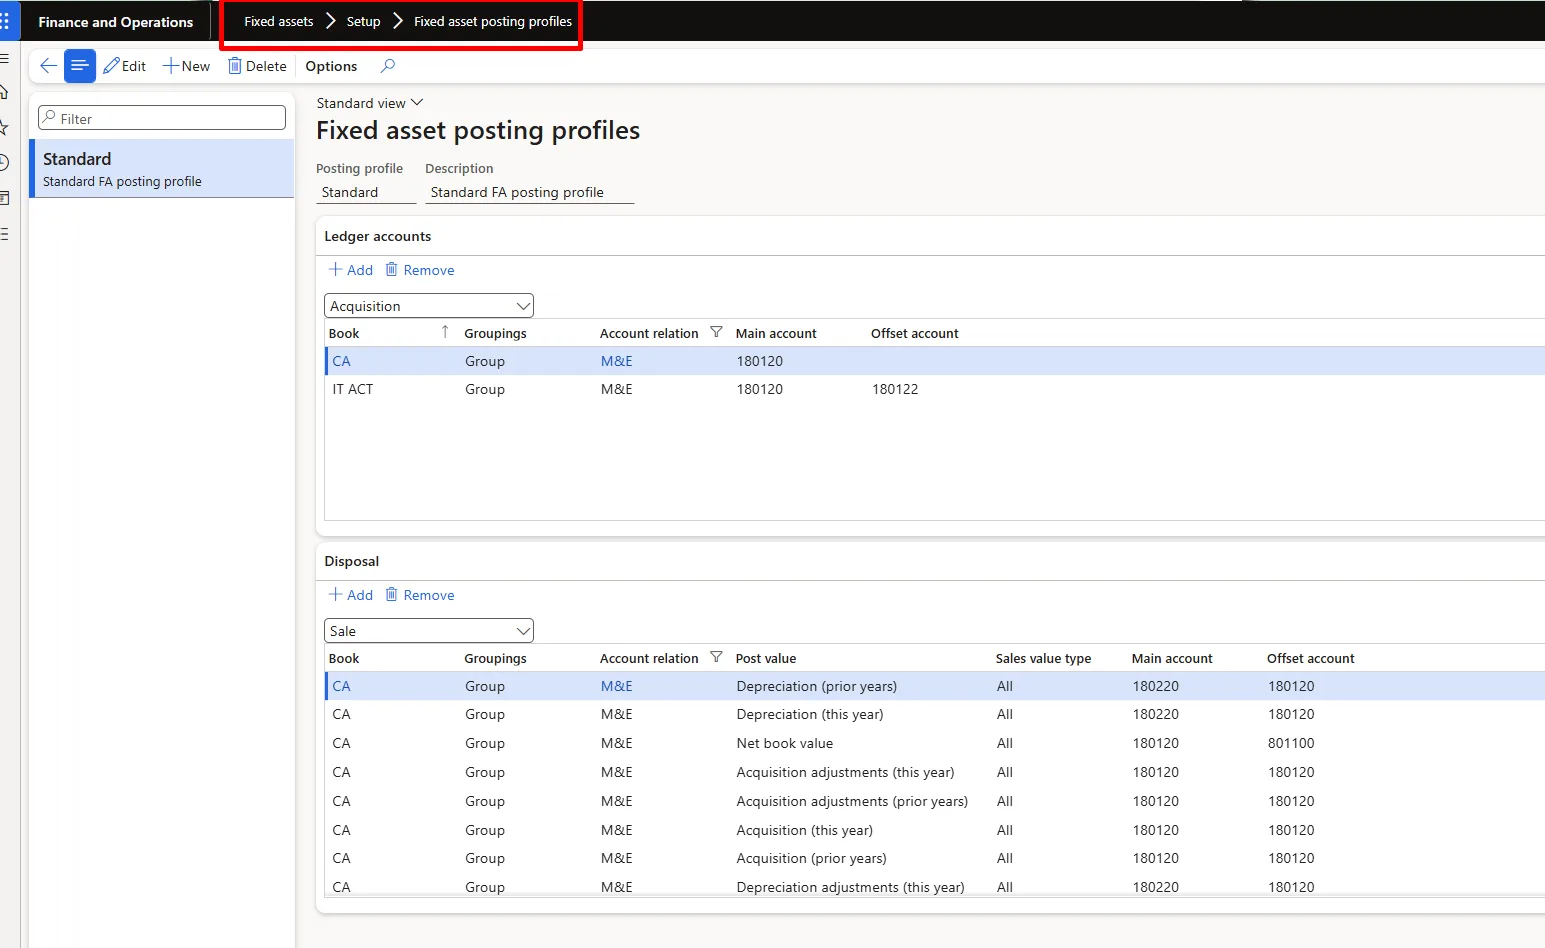
Fixed asset posting profile – Acquisition and Disposal - sale
Acquiring an asset through procurement posts in two steps. The product receipt books an accrual for the physical receipt, and the vendor invoice capitalises the asset and recognises the liability. Physical receipt is therefore not financial acquisition.
1.1 Product Receipt
Accounting entries (vouchers INMF-100000018 and INMF-100000019, 07-10-2026)
Account | Dr / Cr | ME-0004 (INR) | ME-0003 (INR) |
|---|---|---|---|
Fixed assets - receipt | Dr. | 5,00,000.00 | 2,00,000.00 |
Accrued Purchases | Cr. | 5,00,000.00 | 2,00,000.00 |
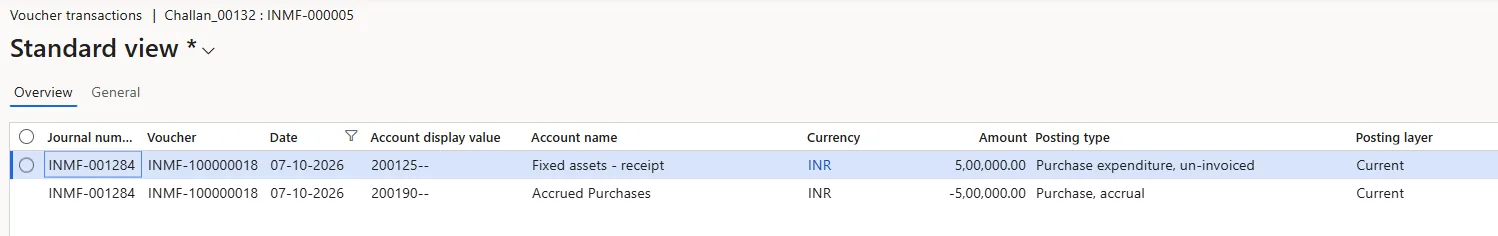
Product receipt voucher
1.2 Vendor Invoice
Posting the vendor invoice reverses the product receipt accrual, recognises the supplier liability and capitalises the asset in both books at once: the CA book posts the acquisition in the current layer, and the derived IT ACT book posts the same acquisition in the tax layer.
Accounting entries (vouchers INMF-110000075 and INMF-110000077, 07-10-2026)
Current layer (Companies Act book):
Account | Dr / Cr | ME-0004 (INR) | ME-0003 (INR) |
|---|---|---|---|
Accrued Purchases (reversal of product receipt accrual) | Dr. | 5,00,000.00 | 2,00,000.00 |
Fixed assets - receipt (reversal of product receipt accrual) | Cr. | 5,00,000.00 | 2,00,000.00 |
Machine & Equipment | Dr. | 5,00,000.00 | 2,00,000.00 |
IGST recoverable (18%) | Dr. | 90,000.00 | 36,000.00 |
Accounts Payable - Domestic | Cr. | 5,90,000.00 | 2,36,000.00 |
Tax layer (Income Tax Act book):
Account | Dr / Cr | ME-0004 (INR) | ME-0003 (INR) |
|---|---|---|---|
Machine & Equipment | Dr. | 5,00,000.00 | 2,00,000.00 |
Fix assets control GL | Cr. | 5,00,000.00 | 2,00,000.00 |
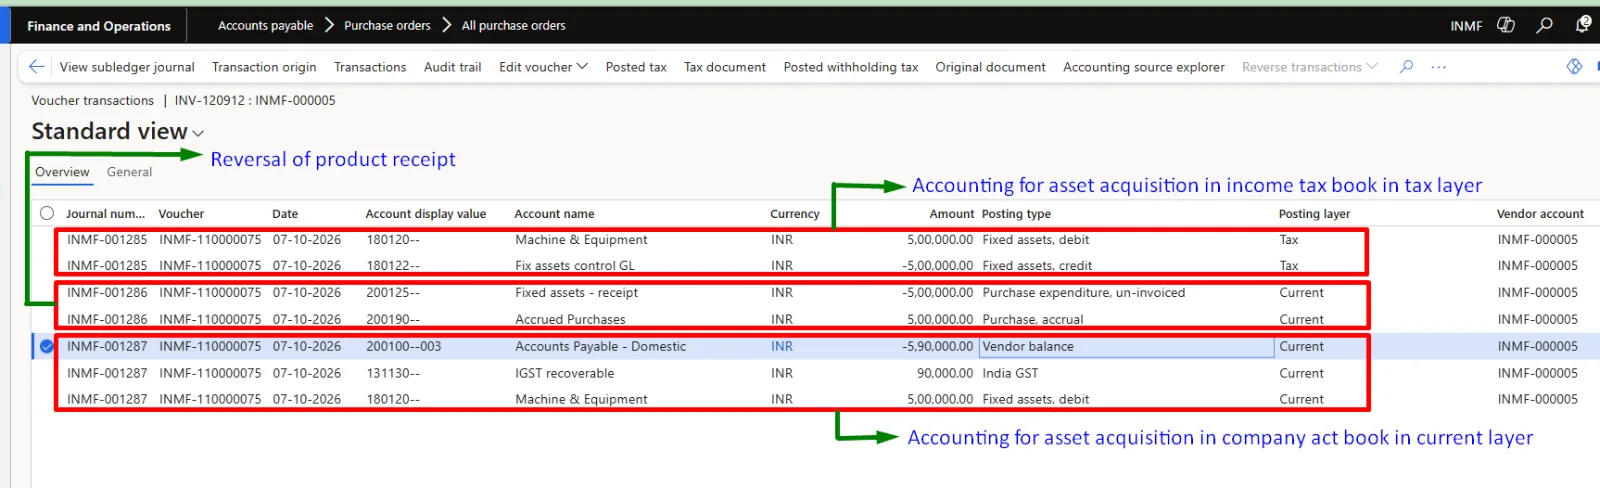
Vendor invoice voucher – current and tax layer
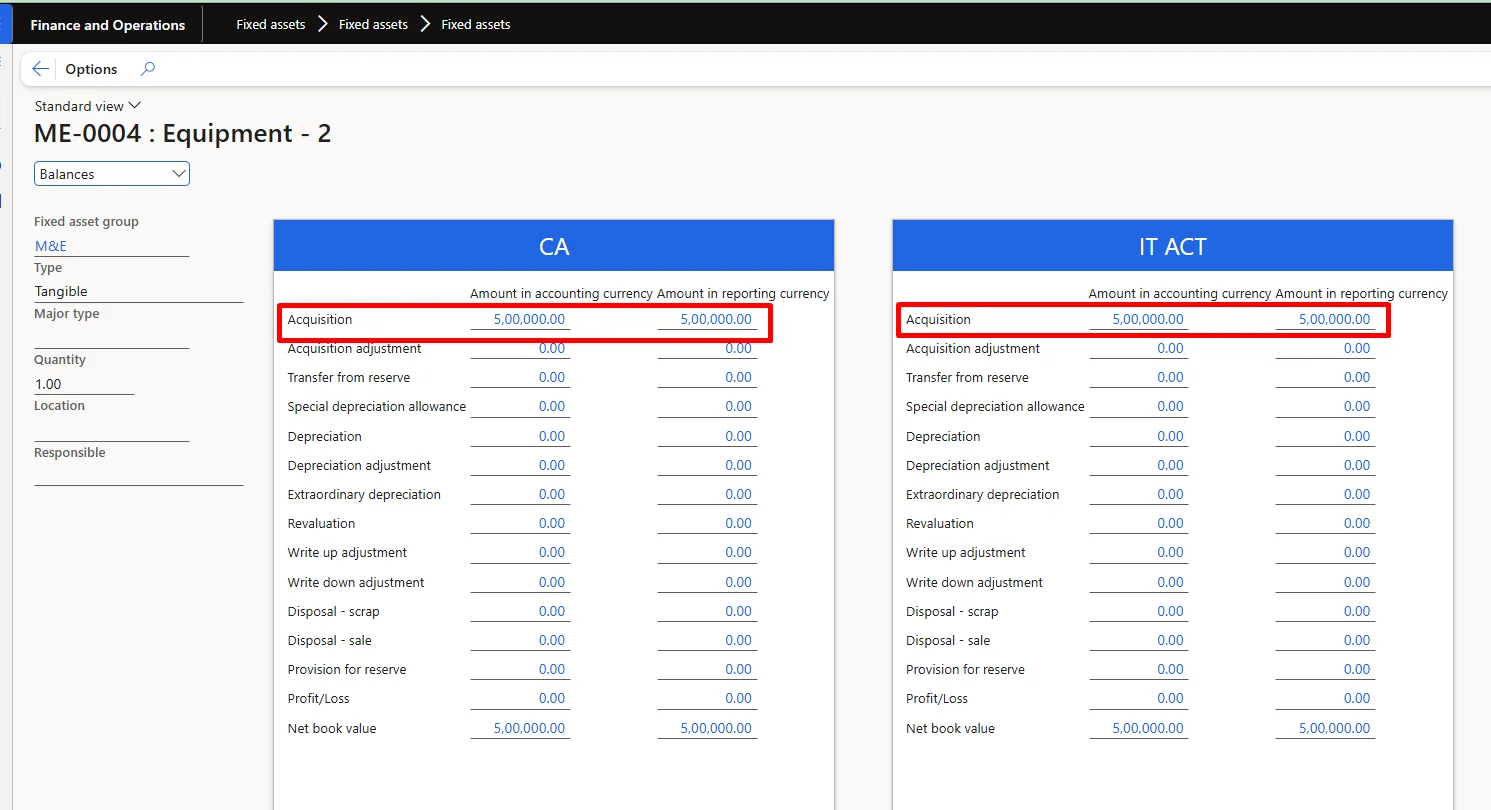
Valuation of ME-0004 after acquisition in both books
Impact: the asset is capitalised on the balance sheet at 5,00,000.00 and 2,00,000.00, with input GST recoverable and a vendor liability. There is no profit and loss impact until depreciation is posted.
Depreciation is calculated separately in each book, because the Companies Act and the Income Tax Act follow different methods. It is therefore not a derived transaction, and each book posts its own vouchers.
2.1 Companies Act Book (Current Layer, Monthly)
Depreciation is calculated per asset, per day, at 20% reducing balance from 07-10-2026.
First depreciation run: 07-10-2026 to 31-10-2026
In the first year, reducing balance depreciation is calculated on the acquisition cost, as the opening net book value equals cost. D365 rounds the daily amount to two decimals and multiplies it by the days in the period.
Step | ME-0003 (INR) | ME-0004 (INR) |
|---|---|---|
Acquisition cost | 2,00,000.00 | 5,00,000.00 |
Annual depreciation at 20% | 40,000.00 | 1,00,000.00 |
Daily depreciation (annual ÷ 365 days in FY 2026-27) | 109.59 | 273.97 |
Days in service, 07-10-2026 to 31-10-2026 | 25 | 25 |
Depreciation for October (daily × 25) | 2,739.75 | 6,849.25 |
Posted (vouchers INMF-000525 / INMF-000526) | 2,739.75 | 6,849.25 |
Every later month uses the same daily amount (30 days in November, 31 in December, 28 in February). ME-0003 was in service for 176 days in the year, giving 109.59 × 176 = 19,287.84, which agrees with the roll forward. Each monthly voucher posts:
- Debit: Depreciation Expense - Tangible Assets
- Credit: Accumulated Depreciation - Machine & Equipment
Period | ME-0003 (INR) | ME-0004 (INR) | Total (INR) |
|---|---|---|---|
07-10-2026 to 31-10-2026 | 2,739.75 | 6,849.25 | 9,589.00 |
November 2026 | 3,287.70 | 8,219.10 | 11,506.80 |
December 2026 | 3,397.29 | 8,493.07 | 11,890.36 |
January 2027 | 3,397.29 | 8,493.07 | 11,890.36 |
February 2027 | 3,068.52 | 7,671.16 | 10,739.68 |
March 2027 | 3,397.29 | 8,493.07 | 11,890.36 |
Total | 19,287.84 | 48,218.72 | 67,506.56 |
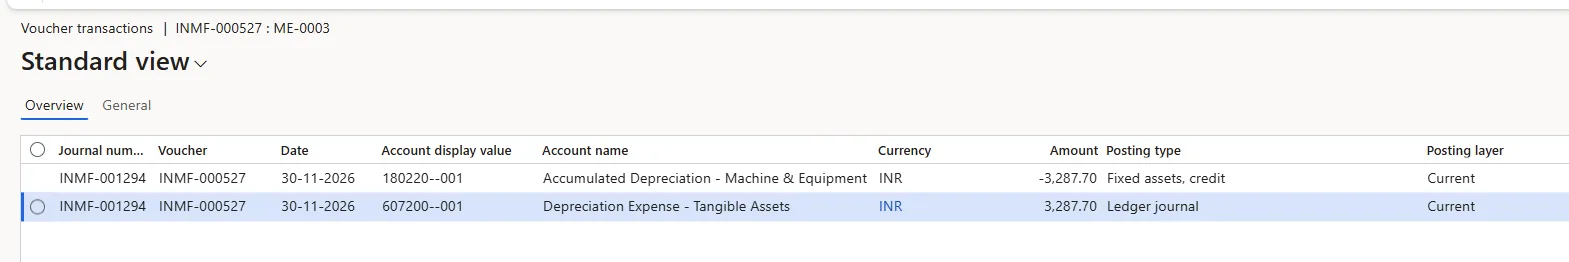
Depreciation voucher – Companies Act book (current layer)
2.2 Income Tax Act Book (Tax Layer, Yearly)
Under the Income-tax Act, depreciation is calculated on the written down value (WDV) of the whole block of assets rather than on each asset. If an asset is put to use for less than 180 days in the year of purchase, only half the rate is allowed.
First (annual) depreciation run: block M&E, FY 2026-27
Step | Amount (INR) |
|---|---|
Opening WDV of block M&E (01-04-2026) | – |
Add: ME-0003 (put to use 07-10-2026, 176 days) | 2,00,000.00 |
Add: ME-0004 (put to use 07-10-2026, 176 days) | 5,00,000.00 |
WDV for depreciation | 7,00,000.00 |
Rate: 15% × 50% (used for less than 180 days) | 7.5% |
Depreciation (7,00,000 × 7.5%) | 52,500.00 |
Posted (voucher FA_T-000000001) | 52,500.80 |
The difference of 0.80 is a system rounding difference. The voucher posts, in the tax layer:
- Debit: Depreciation Expense - Tangible Assets 52,500.80
- Credit: Accumulated Depreciation - Machine & Equipment 52,500.80
Note: under the block method, the sale value of assets sold during the year is also deducted from the block before depreciation. As ME-0003 was sold for 1,75,000.00, the statutory figure would be (7,00,000 – 1,75,000) × 7.5% = 39,375.00. In this example, depreciation was run before the disposal was posted, so the system figure includes ME-0003.
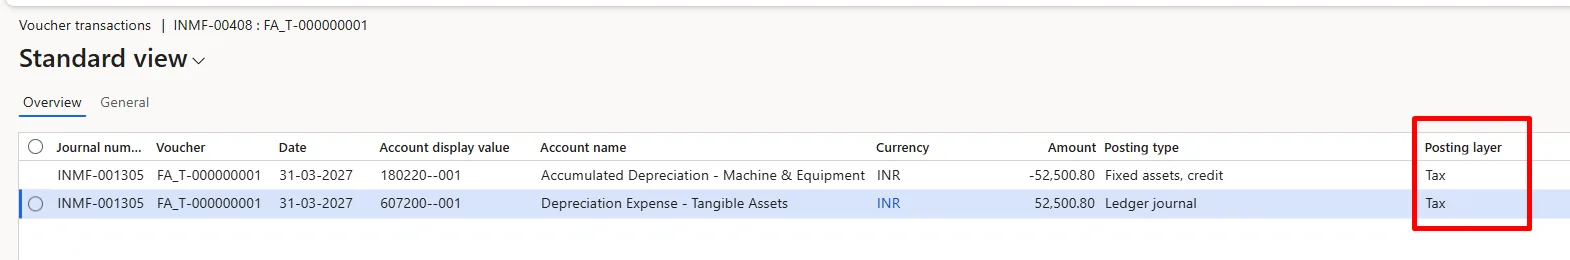
Depreciation voucher – Income Tax Act book (tax layer)
On 31-03-2027, ME-0004 is split twice in the Companies Act book, moving a share of its cost and accumulated depreciation to new assets. Whether the split reaches the general ledger depends on whether the new asset belongs to the same fixed asset group.
3.1 Split within the Same Group: ME-0004 to ME-0005 (50%)
Voucher INMF-000538. In the fixed asset subledger:
Fixed asset transaction | ME-0004 (INR) | ME-0005 (INR) |
|---|---|---|
Acquisition / acquisition adjustment | -2,50,000.00 | 2,50,000.00 |
Depreciation / depreciation adjustment | 24,109.35 | -24,109.35 |
Both assets are in group M&E, so the ledger debit and credit go to the same accounts and net to nil: Machine & Equipment (debit and credit of 2,50,000.00) and Accumulated Depreciation - Machine & Equipment (debit and credit of 24,109.35). The change is only in the fixed asset subledger.
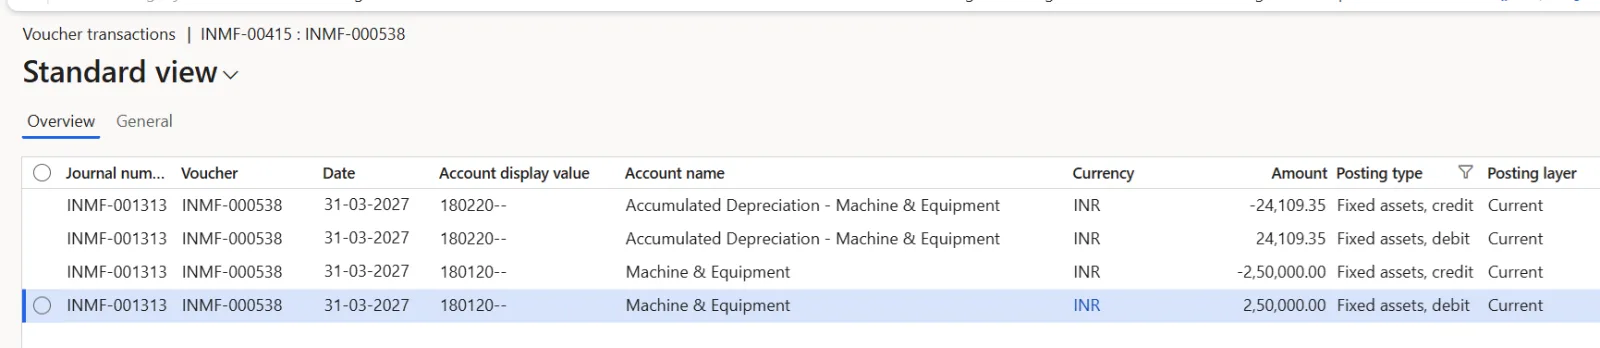
Asset split voucher – same group
3.2 Split to a Different Group: ME-0004 to MEP-0001 (10%)
Voucher INMF-000537. MEP-0001 “Part of Equipment - 2” belongs to group M&E_P, which posts to different accounts, so this split becomes a reclassification in the ledger:
Account | Dr / Cr | Amount (INR) |
|---|---|---|
Equipment & machinery parts | Dr. | 50,000.00 |
Machine & Equipment | Cr. | 50,000.00 |
Accumulated Depreciation - Machine & Equipment | Dr. | 4,821.87 |
Accumulated Depreciation - Parts of Machine & Equipment | Cr. | 4,821.87 |
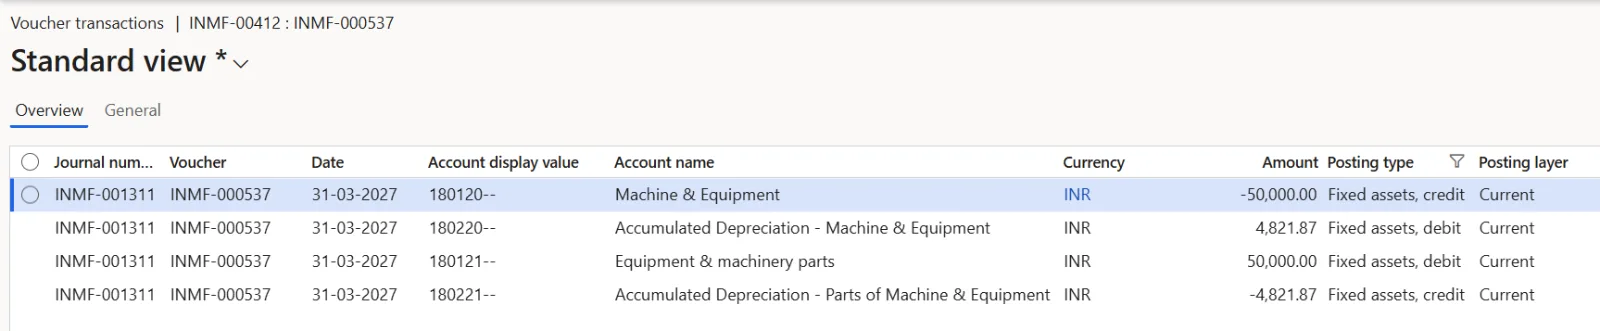
Asset split voucher – reclassification to group M&E_P
After both splits, ME-0004 keeps 40% of its values: cost 2,00,000.00 and accumulated depreciation 19,287.50. The total net book value of the three assets is unchanged at 4,51,781.28.
ME-0003 is sold to Wingtip Toys India Ltd. on 31-03-2027 for 1,75,000.00 plus GST at 18%, through a free text invoice with the fixed asset transaction type Disposal - sale (voucher INMF-30000008).
Gain or loss = Sale proceeds – Net book value
Companies Act book | Amount (INR) |
|---|---|
Acquisition cost | 2,00,000.00 |
Less: accumulated depreciation | 19,287.84 |
Net book value | 1,80,712.16 |
Sale value | 1,75,000.00 |
Loss on sale | 5,712.16 |
Current layer (Companies Act book)
- Remove accumulated depreciation: Debit Accumulated Depreciation - Machine & Equipment 19,287.84; Credit Machine & Equipment 19,287.84.
- Write off the net book value: Debit Gain & Loss - Disposal of Assets 1,80,712.16; Credit Machine & Equipment 1,80,712.16. The net credit to Machine & Equipment equals the cost of 2,00,000.00.
- Recognise the sale: Debit Trade Receivables - Domestic 2,06,500.00; Credit Gain & Loss - Disposal of Assets 1,75,000.00, CGST payable 15,750.00 and SGST payable 15,750.00.
The net result is a debit of 5,712.16 (loss) in Gain & Loss - Disposal of Assets.
Tax layer (Income Tax Act book)
Credit Machine & Equipment 1,75,000.00 and Debit Fix assets control GL 1,75,000.00. Under the block method the sale value is deducted from the block, so no profit or loss is booked on the individual asset.
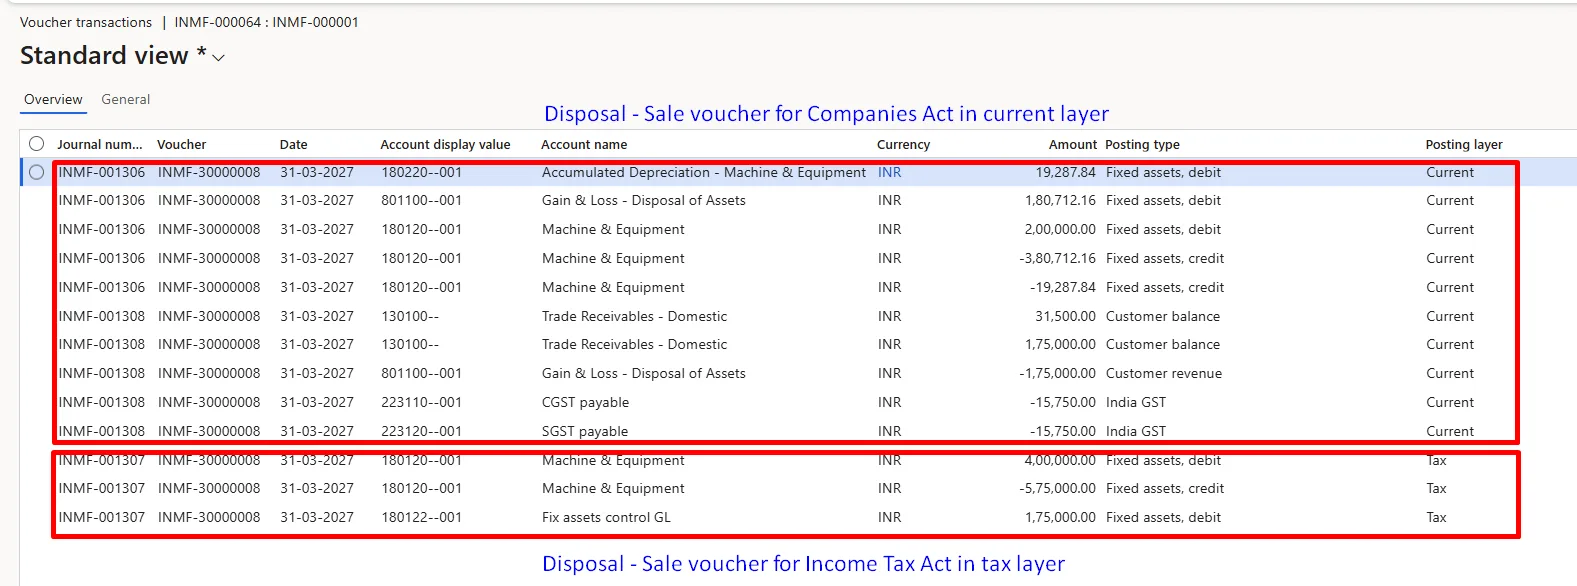
Disposal - sale voucher – current and tax layer
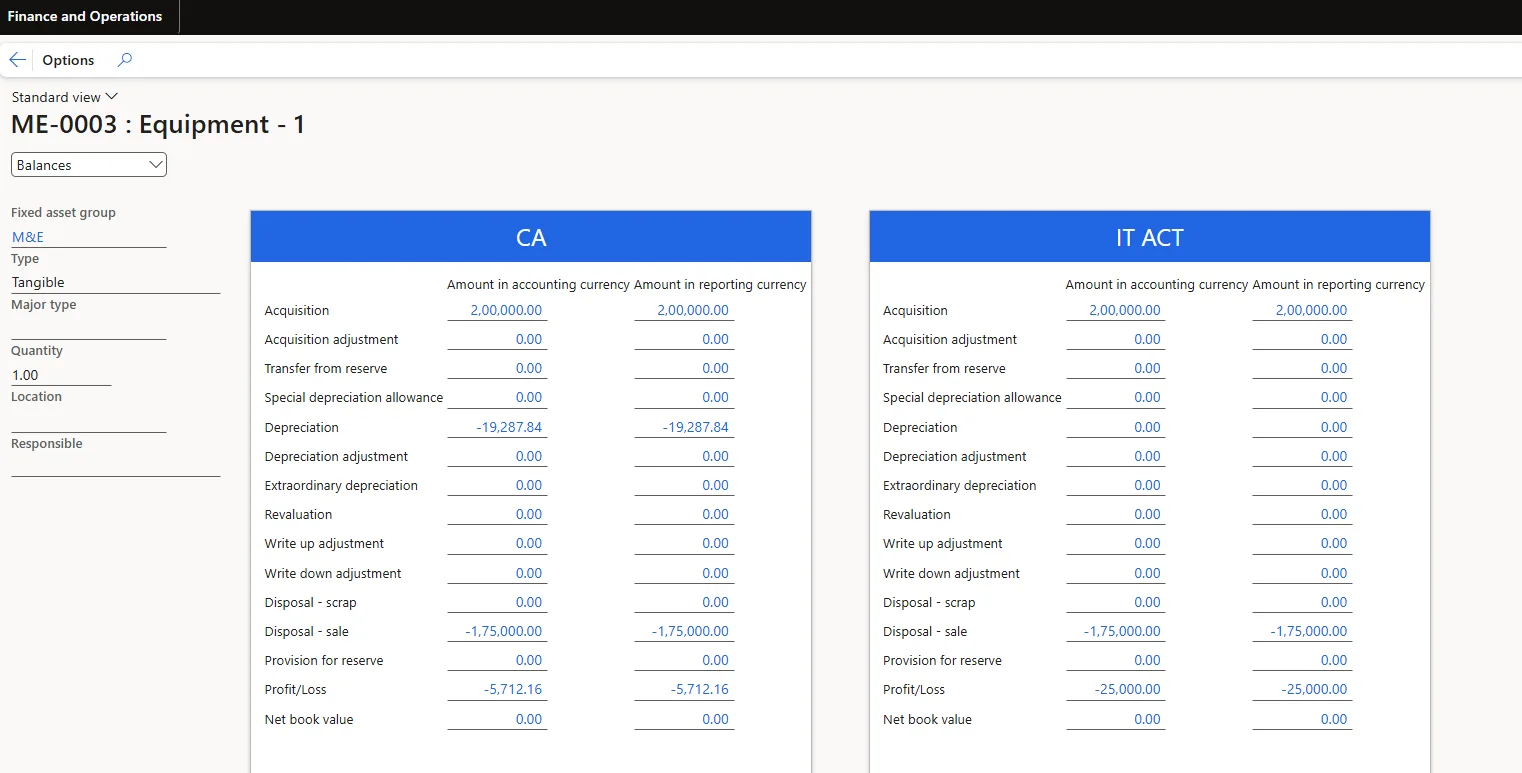
Valuation of ME-0003 after disposal
The fixed asset roll forward report for the Companies Act book, 01-04-2026 to 31-03-2027, summarises the year:
Fixed asset | Name | Group | Cost (INR) | Acc. depreciation (INR) | Net book value (INR) |
|---|---|---|---|---|---|
ME-0003 | Equipment - 1 | M&E | Sold | Sold | – (loss 5,712.16) |
ME-0004 | Equipment - 2 | M&E | 2,00,000.00 | 19,287.50 | 1,80,712.50 |
ME-0005 | Equipment - 3 | M&E | 2,50,000.00 | 24,109.35 | 2,25,890.65 |
MEP-0001 | Part of Equipment - 2 | M&E_P | 50,000.00 | 4,821.87 | 45,178.13 |
Total | 5,00,000.00 | 48,218.72 | 4,51,781.28 |
At period end, the fixed asset subledger should agree with the general ledger:
Group / balance | Subledger (INR) | General ledger account | GL balance (INR) |
|---|---|---|---|
M&E cost | 4,50,000.00 | Machine & Equipment | 4,50,000.00 |
M&E accumulated depreciation | 43,396.85 | Accumulated Depreciation - Machine & Equipment | 43,396.85 |
M&E_P cost | 50,000.00 | Equipment & machinery parts | 50,000.00 |
M&E_P accumulated depreciation | 4,821.87 | Accumulated Depreciation - Parts of Machine & Equipment | 4,821.87 |
Not every business event in the fixed asset cycle reaches the general ledger. Some events are commitments, some update only the fixed asset subledger, and the rest post to one or both posting layers. The table below summarises each stage before the trial balance.
Stage | D365 document / transaction | Accounting impact | Posting layer | Entry posted |
Asset requirement | Purchase requisition | No | – | – |
Commitment to vendor | Purchase order | No | – | – |
Physical receipt | Product receipt (INMF-100000018, INMF-100000019) | Yes (accrual) | Current | Dr Fixed assets - receipt; Cr Accrued Purchases |
Capitalisation | Vendor invoice (INMF-110000075, INMF-110000077) | Yes | Current and Tax (derived book) | Current: reversal of accrual; Dr Machine & Equipment, IGST recoverable; Cr Accounts Payable. Tax: Dr Machine & Equipment; Cr Fix assets control GL |
Asset placed in service | Placed in service date on the book (07-10-2026) | No | – | Starts the depreciation calculation |
Depreciation – Companies Act | Depreciation journal, monthly | Yes | Current | Dr Depreciation Expense; Cr Accumulated Depreciation |
Depreciation – Income Tax Act | Depreciation journal, yearly (FA_T-000000001) | Yes | Tax | Dr Depreciation Expense; Cr Accumulated Depreciation |
Split – same group | Split fixed asset (INMF-000538) | Subledger only; ledger lines net to nil | Current | Dr and Cr to the same accounts |
Split – different group | Split fixed asset (INMF-000537) | Yes (reclassification) | Current | Dr Equipment & machinery parts; Cr Machine & Equipment; accumulated depreciation reclassified |
Disposal – sale | Free text invoice (INMF-30000008) | Yes | Current and Tax | Current: Dr Accumulated Depreciation, Gain & Loss (NBV), Trade Receivables; Cr Machine & Equipment, Gain & Loss (sale value), CGST/SGST. Tax: Dr Fix assets control GL; Cr Machine & Equipment |
Period-end reconciliation | Fixed asset roll forward report | No | – | Confirms the subledger agrees with the general ledger |
Key takeaway: only the current layer feeds the financial statements. The tax layer records the Income Tax Act view of the same events. The trial balance, P&L and balance sheet that follow are therefore prepared from the current layer.
The table below lists every voucher line posted in this cycle, in both posting layers, as extracted from D365 F&O.
Document | Voucher | Date | Account name | Layer | Debit (INR) | Credit (INR) |
|---|---|---|---|---|---|---|
Product receipt | INMF-100000018 | 07-10-2026 | Fixed assets - receipt | Current | 5,00,000.00 | |
Product receipt | INMF-100000018 | 07-10-2026 | Accrued Purchases | Current | 5,00,000.00 | |
Product receipt | INMF-100000019 | 07-10-2026 | Fixed assets - receipt | Current | 2,00,000.00 | |
Product receipt | INMF-100000019 | 07-10-2026 | Accrued Purchases | Current | 2,00,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Machine & Equipment | Tax | 5,00,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Fix assets control GL | Tax | 5,00,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Fixed assets - receipt | Current | 5,00,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Accrued Purchases | Current | 5,00,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Accounts Payable - Domestic | Current | 5,90,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | IGST recoverable | Current | 90,000.00 | |
Vendor invoice | INMF-110000075 | 07-10-2026 | Machine & Equipment | Current | 5,00,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Fixed assets - receipt | Current | 2,00,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Accrued Purchases | Current | 2,00,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Accounts Payable - Domestic | Current | 2,36,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | IGST recoverable | Current | 36,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Machine & Equipment | Current | 2,00,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Machine & Equipment | Tax | 2,00,000.00 | |
Vendor invoice | INMF-110000077 | 07-10-2026 | Fix assets control GL | Tax | 2,00,000.00 | |
Depreciation | INMF-000525 | 31-10-2026 | Depreciation Expense - Tangible Assets | Current | 2,739.75 | |
Depreciation | INMF-000525 | 31-10-2026 | Accumulated Depreciation - Machine & Equipment | Current | 2,739.75 | |
Depreciation | INMF-000526 | 31-10-2026 | Depreciation Expense - Tangible Assets | Current | 6,849.25 | |
Depreciation | INMF-000526 | 31-10-2026 | Accumulated Depreciation - Machine & Equipment | Current | 6,849.25 | |
Depreciation | INMF-000527 | 30-11-2026 | Depreciation Expense - Tangible Assets | Current | 3,287.70 | |
Depreciation | INMF-000527 | 30-11-2026 | Accumulated Depreciation - Machine & Equipment | Current | 3,287.70 | |
Depreciation | INMF-000528 | 30-11-2026 | Depreciation Expense - Tangible Assets | Current | 8,219.10 | |
Depreciation | INMF-000528 | 30-11-2026 | Accumulated Depreciation - Machine & Equipment | Current | 8,219.10 | |
Depreciation | INMF-000529 | 31-12-2026 | Depreciation Expense - Tangible Assets | Current | 3,397.29 | |
Depreciation | INMF-000529 | 31-12-2026 | Accumulated Depreciation - Machine & Equipment | Current | 3,397.29 | |
Depreciation | INMF-000530 | 31-12-2026 | Depreciation Expense - Tangible Assets | Current | 8,493.07 | |
Depreciation | INMF-000530 | 31-12-2026 | Accumulated Depreciation - Machine & Equipment | Current | 8,493.07 | |
Depreciation | INMF-000531 | 31-01-2027 | Depreciation Expense - Tangible Assets | Current | 3,397.29 | |
Depreciation | INMF-000531 | 31-01-2027 | Accumulated Depreciation - Machine & Equipment | Current | 3,397.29 | |
Depreciation | INMF-000532 | 31-01-2027 | Depreciation Expense - Tangible Assets | Current | 8,493.07 | |
Depreciation | INMF-000532 | 31-01-2027 | Accumulated Depreciation - Machine & Equipment | Current | 8,493.07 | |
Depreciation | INMF-000533 | 28-02-2027 | Depreciation Expense - Tangible Assets | Current | 3,068.52 | |
Depreciation | INMF-000533 | 28-02-2027 | Accumulated Depreciation - Machine & Equipment | Current | 3,068.52 | |
Depreciation | INMF-000534 | 28-02-2027 | Depreciation Expense - Tangible Assets | Current | 7,671.16 | |
Depreciation | INMF-000534 | 28-02-2027 | Accumulated Depreciation - Machine & Equipment | Current | 7,671.16 | |
Depreciation | FA_T-000000001 | 31-03-2027 | Depreciation Expense - Tangible Assets | Tax | 52,500.80 | |
Depreciation | FA_T-000000001 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Tax | 52,500.80 | |
Depreciation | INMF-000535 | 31-03-2027 | Depreciation Expense - Tangible Assets | Current | 3,397.29 | |
Depreciation | INMF-000535 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 3,397.29 | |
Depreciation | INMF-000536 | 31-03-2027 | Depreciation Expense - Tangible Assets | Current | 8,493.07 | |
Depreciation | INMF-000536 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 8,493.07 | |
Asset split | INMF-000538 | 31-03-2027 | Machine & Equipment | Current | 2,50,000.00 | |
Asset split | INMF-000538 | 31-03-2027 | Machine & Equipment | Current | 2,50,000.00 | |
Asset split | INMF-000538 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 24,109.35 | |
Asset split | INMF-000538 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 24,109.35 | |
Asset split – reclassification | INMF-000537 | 31-03-2027 | Accumulated Depreciation - Parts of Machine & Equipment | Current | 4,821.87 | |
Asset split – reclassification | INMF-000537 | 31-03-2027 | Equipment & machinery parts | Current | 50,000.00 | |
Asset split – reclassification | INMF-000537 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 4,821.87 | |
Asset split – reclassification | INMF-000537 | 31-03-2027 | Machine & Equipment | Current | 50,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Accumulated Depreciation - Machine & Equipment | Current | 19,287.84 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Gain & Loss - Disposal of Assets | Current | 1,80,712.16 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Machine & Equipment | Current | 2,00,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Machine & Equipment | Current | 3,80,712.16 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Machine & Equipment | Current | 19,287.84 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Trade Receivables - Domestic | Current | 31,500.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Trade Receivables - Domestic | Current | 1,75,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Gain & Loss - Disposal of Assets | Current | 1,75,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | CGST payable | Current | 15,750.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | SGST payable | Current | 15,750.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Machine & Equipment | Tax | 4,00,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Machine & Equipment | Tax | 5,75,000.00 | |
Disposal – sale | INMF-30000008 | 31-03-2027 | Fix assets control GL | Tax | 1,75,000.00 | |
Total | 45,56,438.58 | 45,56,438.58 |
8.1 Current layer trial balance
The trial balance below is for the current layer, which feeds the financial statements. Opening balances are the closing balances of Part 3 (Order to Cash).
Main Account Name | Opening Balance | Debit (INR) | Credit (INR) | Closing Balance |
|---|---|---|---|---|
Bank Account - INR | -1,95,000.00 | – | – | -1,95,000.00 |
Trade Receivables - Domestic | – | 2,06,500.00 | – | 2,06,500.00 |
CGST recoverable | 81,900.00 | – | – | 81,900.00 |
SGST recoverable | 81,900.00 | – | – | 81,900.00 |
IGST recoverable | – | 1,26,000.00 | – | 1,26,000.00 |
TDS Recoverable | 12,000.00 | – | – | 12,000.00 |
Work in process - Manufacturing | 2,50,000.00 | – | – | 2,50,000.00 |
Machine & Equipment | – | 11,50,000.00 | 7,00,000.00 | 4,50,000.00 |
Equipment & machinery parts | – | 50,000.00 | – | 50,000.00 |
Accumulated Depreciation - Machine & Equipment | – | 48,219.06 | 91,615.91 | -43,396.85 |
Accumulated Depreciation - Parts of Machine & Equipment | – | – | 4,821.87 | -4,821.87 |
Accounts Payable - Domestic | – | – | 8,26,000.00 | -8,26,000.00 |
Fixed assets - receipt | – | 7,00,000.00 | 7,00,000.00 | – |
Accrued Purchases | – | 7,00,000.00 | 7,00,000.00 | – |
TDS on Purchase | -81,900.00 | – | – | -81,900.00 |
CGST payable | -60,000.00 | – | 15,750.00 | -75,750.00 |
SGST payable | -60,000.00 | – | 15,750.00 | -75,750.00 |
Sales - Finished Goods | -6,00,000.00 | – | – | -6,00,000.00 |
Issue-Finished Goods | -1,19,846.80 | – | – | -1,19,846.80 |
Raw Material Consumption | -12,308.50 | – | – | -12,308.50 |
COGS - Finished Goods | 1,19,846.80 | – | – | 1,19,846.80 |
WIP - Production | -2,50,000.00 | – | – | -2,50,000.00 |
Cash Discounts | 2,100.00 | – | – | 2,100.00 |
Raw Materials Receipts | 8,19,000.00 | – | – | 8,19,000.00 |
Finished Goods - Inventory | 2,62,308.50 | – | – | 2,62,308.50 |
Direct Labor Applied | -2,50,000.00 | – | – | -2,50,000.00 |
Depreciation Expense - Tangible Assets | – | 67,506.56 | – | 67,506.56 |
Gain & Loss - Disposal of Assets | – | 1,80,712.16 | 1,75,000.00 | 5,712.16 |
Total | – | 32,28,937.78 | 32,28,937.78 | – |
Observations from the trial balance:
- Fixed assets - receipt and Accrued Purchases net to zero, confirming that the product receipt accruals were reversed on invoicing.
- Machine & Equipment closes at 4,50,000.00: 7,00,000.00 acquired, less 2,00,000.00 for ME-0003 sold and 50,000.00 reclassified to Equipment & machinery parts. The split to ME-0005 nets to nil.
- Accumulated depreciation across both accounts totals 48,218.72: 67,506.56 charged, less 19,287.84 reversed on the sale of ME-0003.
- Accounts Payable of 8,26,000.00 and Trade Receivables of 2,06,500.00 remain open, as no vendor payment or customer receipt is posted in this part.
8.2 Tax layer trial balance
Tax layer balances (Income Tax Act book, not part of the financial statements):
Account | Balance (INR) |
|---|---|
Machine & Equipment (block WDV before depreciation) | 5,25,000.00 |
Fix assets control GL | -5,25,000.00 |
Depreciation Expense - Tangible Assets | 52,500.80 |
Accumulated Depreciation - Machine & Equipment | -52,500.80 |
Particulars | Amounts (2026-27) |
|---|---|
Revenue from Operations | 6,00,000.00 |
Other Income (vendor cash discount) | 900.00 |
Total Income | 6,00,900.00 |
Changes in Inventories of Finished Goods (COGS) | 1,19,846.80 |
Absorbed production costs (Direct Labor Applied) | -2,50,000.00 |
Depreciation and Amortisation Expense | 67,506.56 |
Other Expenses (customer cash discount 3,000.00 + loss on sale of asset 5,712.16) | 8,712.16 |
Total Expenses | -53,934.48 |
Profit Before Tax | 6,54,834.48 |
Profit After Tax for the Year | 6,54,834.48 |
Total Comprehensive Income for the Year | 6,54,834.48 |
The Acquire to Dispose cycle reaches the Profit and Loss statement only through depreciation of 67,506.56 and the loss on sale of 5,712.16. The asset purchases are capitalised, and the splits have no profit and loss impact.
Particulars | Amounts (2026-27) |
|---|---|
ASSETS | |
Non-current Assets | |
Property, Plant and Equipment – Machine & Equipment (4,50,000.00 – 43,396.85) | 4,06,603.15 |
Property, Plant and Equipment – Equipment & machinery parts (50,000.00 – 4,821.87) | 45,178.13 |
Current Assets | |
Inventories (raw materials 8,06,691.50 + finished goods 1,42,461.70) | 9,49,153.20 |
Trade Receivables | 2,06,500.00 |
Cash and Cash Equivalents | -1,95,000.00 |
Current Tax Assets (TDS receivable) | 12,000.00 |
Other Current Assets (GST input: CGST, SGST and IGST) | 2,89,800.00 |
TOTAL ASSETS | 17,14,234.48 |
EQUITY AND LIABILITIES | |
Other Equity | 6,54,834.48 |
Trade Payables | 8,26,000.00 |
Other Current Liabilities (GST payable) | 1,51,500.00 |
Current Tax Liabilities (TDS payable) | 81,900.00 |
TOTAL EQUITY AND LIABILITIES | 17,14,234.48 |
Property, plant and equipment of 4,51,781.28 now appears alongside the inventory and working capital balances carried from Parts 1 to 3. The asset purchases of 7,00,000.00 plus input GST are still owed to the vendor, and the disposal proceeds of 2,06,500.00 are still receivable from the customer.
Every stage of the Acquire to Dispose cycle can be traced from the business document to the fixed asset transaction, the voucher, the general ledger and finally the financial statements:
Product receipt (accrual) → Vendor invoice (capitalisation) → Depreciation → Split → Disposal → Gain/Loss
When reviewing fixed asset accounting, the key questions are which book and posting layer a transaction affects, which posting profile account it uses, and what entry finally reaches the general ledger.